Global operators now run most of Africa’s main ports, new rail is resetting old corridors, and the EU’s deforestation rules start in December 2026. This guide covers the market, the corridors, ports, trade policy and who funds African logistics, for founders who already have customers and want to grow.
In this guide
Earlier stage? If you are still choosing what to build, start with logistics startup ideas in Africa.
How big is the African logistics market?
The short answer
Africa’s outsourced logistics market is roughly $150–250 billion a year, inside a total logistics spend of about $370–510 billion once in-house transport and storage are counted. Venture money is a sliver of that. Growth for a scaleup comes from corridors, ports and policy that are changing now, not from the headline size.
- Opportunities cluster where a corridor is changing: new rail, new port capacity or a new governance body. Those changes reset routes, prices and who the incumbents are.
- Global operators now hold most major ports, so the competition, and the openings, have moved inland: depots, drayage, clearing and hinterland warehousing.
- AfCFTA is a slow tailwind, not an immediate market. The EU’s deforestation rules (from 30 December 2026) are the most time-sensitive opening.
- Logistics and transport overtook fintech as Africa’s most-funded startup sector in January–September 2026, but one company took most of the money. For logistics, debt matters more than equity.
Scope. Pan-African, with more depth on East Africa (Kenya, Uganda, Tanzania, Rwanda, Ethiopia) and Nigeria, where the most operators and data are documented. Ghana, Côte d’Ivoire, Egypt, Morocco and South Africa come in where they matter.
Market size, and why the numbers disagree
Most published segment figures disagree by 2–9×. The table gives ranges, names the source behind each end, and adds a cross-check where one is possible. Treat every figure as an order of magnitude, not a forecast to build a plan on.
Top-down cross-check (our estimate). Africa’s combined GDP is about $3.4 trillion (AfCFTA framing, via Freight News). South Africa, the only African country that measures it, spends about 11–12% of GDP on logistics (Stellenbosch Logistics Barometer, via tralac); developed economies spend under 10%. Applying 11–15% to continental GDP gives $370–510 billion of total logistics cost. The commercial market estimate of about $185 billion is 36–50% of that, a plausible outsourced share.
| Segment | Estimate (2025 unless noted) | Sources and method | Confidence |
|---|---|---|---|
| Total logistics cost (in-house + outsourced) | $370–510B | Our calculation: 11–15% × $3.4T GDP | Low–medium |
| Third-party logistics and warehousing | ~$185B; ~6.4% growth a year to 2031–32 | Ken Research; for context, Mordor puts Middle East + Africa at $305B (Mordor) | Medium |
| Road freight | ~$80–100B | Road ≈ 51% of logistics revenue (Ken Research) × $185B | Medium |
| — of which cross-border road freight | ~$10B ($9.8B in 2025) | Mordor | Medium |
| Freight forwarding | ~$18B | Ken Research | Medium |
| E-commerce sales (GMV, not logistics) | $40–75B; one outlier at $361B | Statista $40.5B (StatTimes); Knight Frank >$75B (Ecofin); IMARC $361B likely includes B2B (Freight News) | Low |
| E-commerce logistics and last mile | ~$4–11B | Our calculation: 10–15% of $40–75B GMV; last mile is about half of e-commerce logistics cost (TechCabal Insights) | Low |
| Cold chain logistics | ~$10–15B | $10.9B (2024, GCCA); $14.5B (2025) and $15.0B (2026) by Mordor; $12.9B by MarkNtel (MarkNtel) | Medium |
| Warehousing (Middle East + Africa) | $83B today → $132B by 2030 | World Bank, via Ecofin; no reliable Africa-only figure found | Low for Africa alone |
| Air cargo | ~2.1% of global air cargo volume | IATA, via Nairametrics | High (share); no reliable value figure |
| Two-wheelers (all) | ~$9B | Mordor, via Research and Markets | Medium |
| — electric two-wheelers | ~70,000 units (2025); $0.4B (2023) → $2.6B (2031) forecast | IEA, via Ecofin; forecast via Mobility Rising | High (units); low (forecast) |
| New heavy trucks | ~$2.7B a year ($2.73B in 2025) | Mordor; with truck-finance penetration under 1%, most of this is cash or informal credit | Medium |
Why the numbers diverge. Reports mix up four things: Africa vs Middle East + Africa, gross sales vs logistics revenue, formal vs total activity, and different base years. E-commerce is the extreme case, from $40 billion to $361 billion. When a pitch deck or report cites a market size, check which of these it uses.
How to use these figures.
- Venture money is small relative to the market. Logistics startups raised about $472 million in H1 2026, well under 1% of the roughly $185 billion third-party market.
- Size the serviceable slice, not the continent. Start from one corridor or city: trucks or parcels per day × price × realistic share. Corridor and port data (TEU, truck counts, parcel volumes) are usually more reliable than continental reports.
- Prefer measured volumes to market values. TEU throughput, e-bike units, cold-room counts and air cargo tonnes come from operators and IATA. Dollar market sizes come from models.
Africa’s main trade corridors
A handful of port-to-hinterland corridors carry most of Africa’s containerised and bulk trade. Opportunities cluster where a corridor is changing.
| Corridor | Route | Main cargo | What is changing | Relevance for scaleups |
|---|---|---|---|---|
| Northern Corridor | Mombasa – Nairobi – Kampala – Kigali – eastern DRC, South Sudan | Containers, fuel, consumer goods inbound; tea, coffee, horticulture outbound | Standard Gauge Railway to the Naivasha inland container depot; ongoing road–rail competition | Inland depots, last-leg trucking from Naivasha, cross-border visibility to Uganda and Rwanda |
| Central Corridor | Dar es Salaam – Dodoma – Rwanda, Burundi, eastern DRC | Containers, construction inputs, minerals | Tanzania’s SGR being built in phases; Dar port concession to DP World (2023) | Rail feeder services, bonded warehousing, Burundi/DRC transit |
| Lobito Corridor | Lobito (Angola) – DRC Copperbelt – Zambia | Copper and cobalt outbound; return-cargo potential inbound | US/EU-backed rail upgrade; first copper and cobalt shipments via the corridor in February 2026; Angola–Zambia greenfield link at EPC stage (Engineering News, Mining Weekly) | Backhaul cargo for mining trains, agri-export logistics, corridor services in Angola and Zambia |
| Abidjan–Lagos | Abidjan – Accra – Lomé – Cotonou – Lagos | Consumer goods, informal trade, fuel | Highway project planned; five borders in about 1,000 km | Border-crossing services, multi-currency payments, cross-border parcel networks |
| Lomé and Tema hubs | Togo and Ghana ports to the Sahel (Burkina Faso, Niger, Mali) | Transhipment, Sahel imports | Lomé’s rise as a transhipment hub; Sahel insecurity disrupts routes | Transit tracking, security-aware routing, insurance |
| Maputo Corridor | Johannesburg/Gauteng – Maputo | Coal, chrome, minerals, citrus | Heavy truck congestion due to South African rail constraints | Truck-appointment and staging systems, rail–road switching |
| North–South | Durban – Beitbridge – Zimbabwe – Zambia – DRC | Mining inputs, consumer goods | Beitbridge remains a chronic bottleneck | Border pre-clearance, driver services, fleet finance |
| Djibouti Corridor | Djibouti – Addis Ababa | Almost all of Ethiopia’s imports | Electric railway in place but underused; trucks still dominate | Inland logistics in Ethiopia’s opening market |
Most openings sit at the handovers nobody owns: rail to road, port to depot, one country’s customs to the next.
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| First- and last-mile trucking at new rail terminals | Shippers, rail operators | Medium | Medium | Contract with one terminal (Naivasha ICD, SGR stations, Lobito) |
| Inland container depots and bonded yards | Shipping lines, importers | High | Low | Partner with a port concessionaire |
| Corridor visibility and transit tracking | Shippers, forwarders, insurers | Low | Medium | One corridor, one cargo type |
| Backhaul cargo for mineral corridors | Agri exporters, input importers | Medium | Low | Return loads on Lobito and Copperbelt trains |
| Border-crossing services, Abidjan–Lagos | SMEs, traders | Low | Medium | One border pair, e.g. Seme |
How sure are these facts? The corridor geography and cargo mix are stable. Project timelines (SGR phases, Lobito’s Zambia link, the Abidjan–Lagos highway) slip often.
Ports and maritime in 2025–26
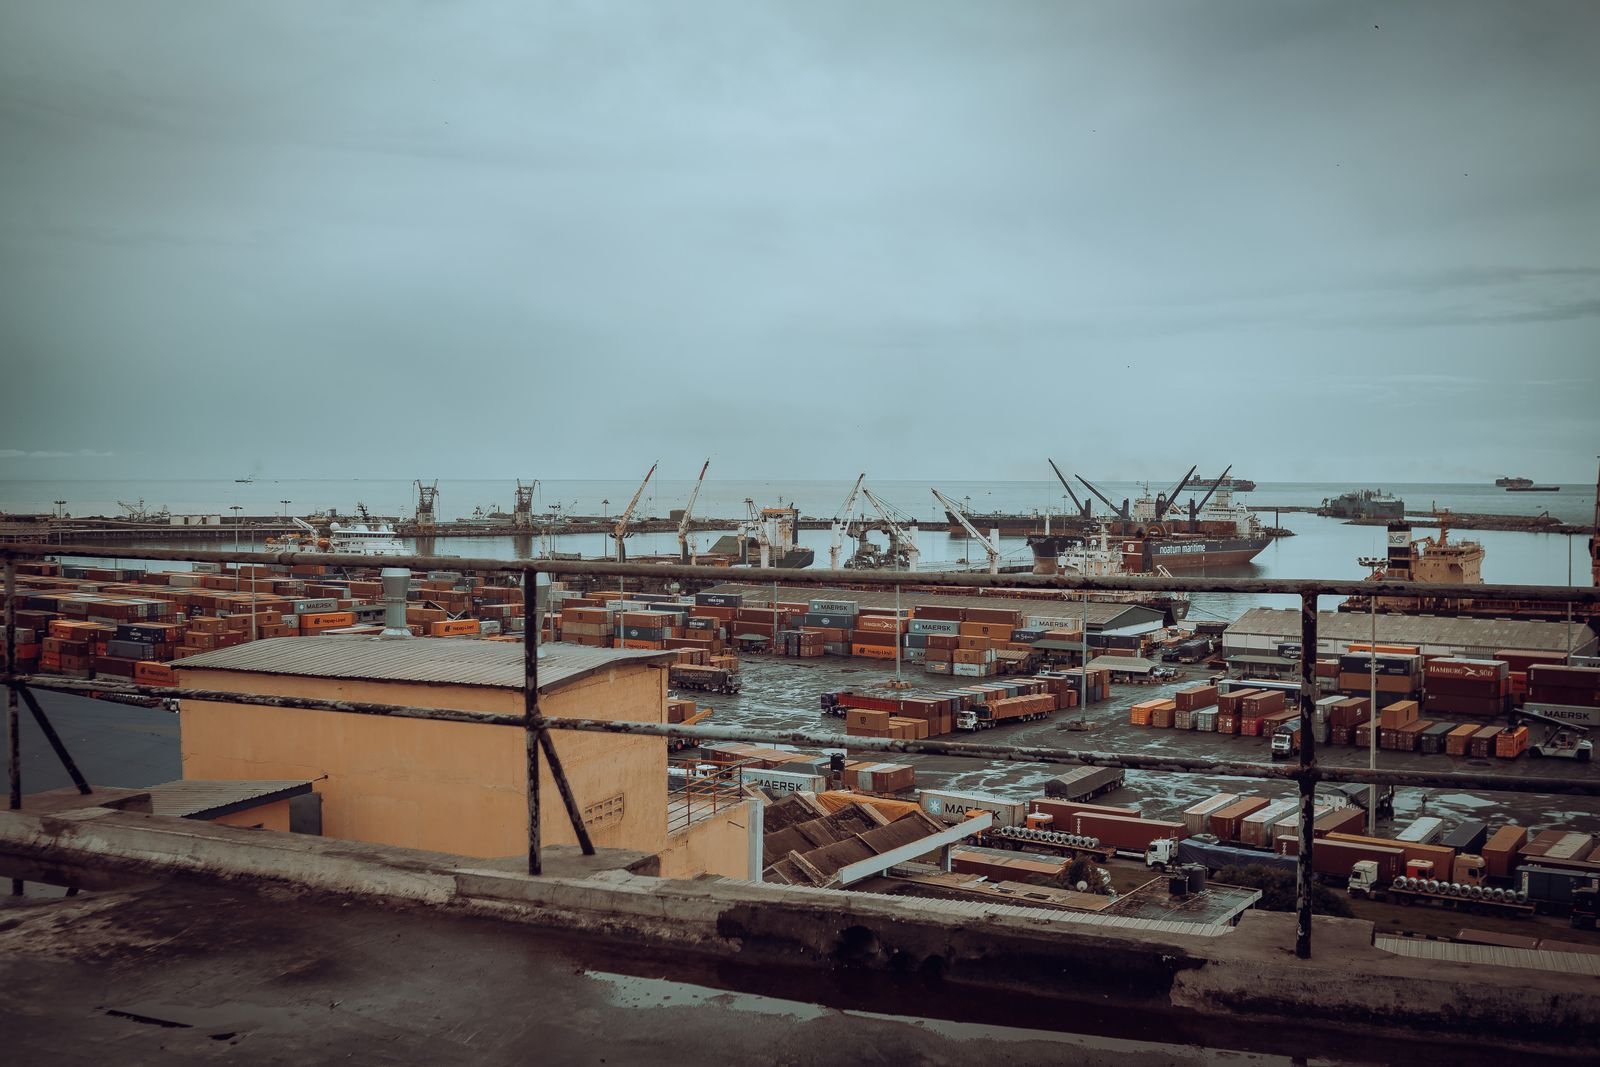
African ports are being handed to global operators under long concessions, and the competition is moving inland. Gulf-based operators (DP World, AD Ports) and the shipping lines’ own terminal arms (MSC’s AGL, Hapag-Lloyd, CMA CGM) now control most major gateways.
| Port | Operator | Latest development |
|---|---|---|
| Dar es Salaam (Tanzania) | DP World (30-year concession from October 2023, about two-thirds of the port); AD Ports–Adani JV on Container Terminal 2 | DP World awarded the redevelopment contract in August 2026 (AGBI); initial $250M, up to $1B over the concession (Container News) |
| Mombasa and Lamu (Kenya) | Kenya Ports Authority | The Treasury’s PPP unit approved the feasibility report in August 2026 for concessions of Mombasa berths 11–14, Mombasa Container Terminal 1, Lamu container terminal berths 1–3 and the Lamu Special Economic Zone, clearing KPA to open bids (Business Daily) |
| Lekki (Nigeria) | CMA CGM-operated container terminal | Grew from 287,000 TEU (2024) to about 500,000 TEU (2025), still well below 1.2M TEU phase-1 capacity; now transships to Togo, Ghana and Côte d’Ivoire (Daily Trust) |
| Luanda and Lobito (Angola) | AD Ports (Luanda multipurpose, 20 years); DP World (Luanda containers); AGL/MSC (Lobito) | Capacity upgrades linked to the Lobito Corridor |
| Dakar, Banana (DRC), Maputo | DP World with Hapag-Lloyd capacity deals | Hapag-Lloyd expects over 1M TEU of Africa volume in 2026 (Marine Insight); DP World’s $1.2B Ndayane port in Senegal under way |
| Kobe-Kobe (Gabon) | AGL (MSC) | Convention signed April 2026 for a port planned together with its logistics zone (Capmad) |
The Red Sea reset. Since late 2023, most container ships avoided the Red Sea and sailed around the Cape of Good Hope. East African ports such as Mombasa and Dar es Salaam gained about 10% in connectivity during the diversion (Supply Chain Digital). A gradual return started in 2026: by September, Maersk had moved more than 30% of its around-Africa volume back to Suez, and MSC restored several services (Portogente). The return releases about 6% of global vessel capacity, which pushes freight rates down (Zencargo). Security in the Gulf and the Strait of Hormuz remains a wild card.
- For East Africa: Europe–East Africa transit times should shorten and ocean rates soften. Some of the extra calls that came with the Cape diversion will disappear, especially at South and West African ports.
- For West Africa: Lekki’s spare capacity and transhipment push compete with Lomé, Tema and Abidjan. Port choice will increasingly depend on inland logistics, not just quay capacity.
- The bottleneck moves inland. Lekki reported 16-day cargo dwell time in 2025 despite fast vessel turnaround (Gazette NGR). Faster quays expose slow customs, trucking and depots.
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| Drayage and port-gate trucking | Shipping lines, importers | Medium | Medium | Concession start-ups: Dar es Salaam, the Mombasa and Lamu concessions |
| Inland container depots and empty-container depots | Shipping lines | High | Low | Partner with a terminal operator |
| Truck appointment and port-gate software | Terminals, transporters | Low | Low | Lekki’s 16-day dwell time shows the need |
| Container tracking and demurrage alerts | Importers, forwarders | Low | Medium | Importers on one port |
| Transit from transhipment hubs to landlocked markets | Shippers in the Sahel and Great Lakes | Medium | Low | Lekki or Lomé into the Sahel; Dar es Salaam into DRC and Burundi |
New concessions are the moments to win contracts.
AfCFTA: what is real for logistics in 2026
The AfCFTA has moved from negotiation to slow, uneven implementation. The legal framework is now mostly complete: rules of origin for the last holdouts, automotive and textiles, were concluded by early 2026 (Freight News). But duty-free trade still depends on each country gazetting tariff cuts and its customs applying them. African leaders themselves flagged slow tariff reductions in February 2026 (AU Assembly decision, via tralac).
| Element | Status (October 2026) | What it means for logistics operators |
|---|---|---|
| Tariff schedules | 48–49 provisional schedules submitted and verified; Category B (sensitive goods) reductions due to start January 2026 (tralac, July 2025) | Duty savings are real only on lanes where both countries have gazetted and applied cuts. Check lane by lane. |
| Rules of origin | Concluded, including automotive (40% African content) and textiles; focus now on consistent application by customs (Freight News) | Demand for origin certificates, supplier-declaration management and audit trails |
| Guided Trade Initiative | Started in 2022 with seven pilot countries: Cameroon, Egypt, Ghana, Kenya, Mauritius, Rwanda and Tanzania (trade.gov); Tunisia and other countries joined later (African Liberty); volumes still modest | Early-mover shippers on GTI lanes need forwarders that know the paperwork |
| Digital Trade Protocol | Adopted by the AU; not yet in force (needs 22 ratifications). Nigeria first to secure approval; leaders target ratification by end-2026 (Mondaq) | Future common rules for e-invoices, digital IDs, cross-border payments and data; pilots (ADAPT) in Kenya, Morocco and Nigeria |
| Payments | PAPSS settles intra-African payments in local currencies | Lowers FX friction for freight payments |
| Trade in services | 25 schedules adopted across five priority sectors, including transport (AfCFTA Secretariat) | Gradual opening of cross-border transport and logistics services |
The honest read. AfCFTA is a slow tailwind, not an immediate market. Non-tariff barriers (border delays, standards, transit fees, informal payments) still matter more than tariffs for most cargo. Intra-African trade grew 5.5% to about $213.8 billion in 2025, according to Afreximbank’s African Trade Report 2026 (Nairametrics).
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| AfCFTA compliance services (origin documents, certificates, duty claims) | Manufacturers, exporters | Low | Low | One lane already trading under the Guided Trade Initiative |
| Rules-of-origin software | Exporters, customs brokers | Low | Low | Automotive and textile exporters now that rules are concluded |
| AfCFTA landed-cost calculators | Shippers, SMEs | Low | Low | Embedded in forwarders’ quoting tools |
| Digital trade infrastructure (e-invoicing, digital IDs, payments) | Governments, platforms | Medium | Medium | Pilots under ADAPT in Kenya, Morocco and Nigeria |
Timing is the main risk, so start on lanes where trade already flows (EAC, ECOWAS).
The EU–Africa corridor: deforestation rules, parcel duties and Global Gateway
Three EU-side changes in 2026 reshape logistics between Europe and Africa: Global Gateway money for corridors, the deforestation regulation (EUDR) that turns traceability into a market-access requirement, and the end of duty-free treatment for small parcels. Meanwhile Chinese platforms, not European ones, are winning the cross-border e-commerce flow into Africa.
| Driver | What changed | Date | Logistics impact |
|---|---|---|---|
| Global Gateway strategic corridors | EU support concentrated on priority corridors, including Abidjan–Lagos, Abidjan–Ouagadougou, the Northern Corridor and Lobito (EEAS); EU corridor investment forum in Abidjan, March–April 2026 (VC4A) | Ongoing | Project pipelines for roads, rail, ports and trade facilitation; procurement and partnership openings |
| EUDR (deforestation regulation) | Coffee, cocoa, palm oil, rubber, timber, soy and cattle must have geolocated, deforestation-free supply chains. Dates set by Regulation (EU) 2025/2650 (EY); the EU has ruled out a further delay (Ecofin) | Large and medium operators from 30 December 2026; micro and small from 30 June 2027 | Demand for farm mapping, traceability data and segregated logistics in Côte d’Ivoire, Ghana, Uganda, Kenya and Ethiopia |
| EU customs reform: end of the €150 de minimis | Flat €3 duty per item category on low-value e-commerce parcels via IOSS; EU-wide handling fee (about €2) expected; national fees already in Italy and Romania (ShippyPro; FedEx) | €3 duty from 1 July 2026; handling fee from about November 2026; EU Customs Data Hub 2028 | Raises the cost of direct-to-consumer parcels into the EU; favours bulk shipping to EU warehouses |
| Chinese platforms in Africa | Temu launched in Nigeria (November 2024) and opened local-warehouse dispatch in South Africa via 3PLs (EWN); Shein and Temu took about 37% of South Africa’s online apparel market (TechCabal); JD Express delivers to 11 African countries | 2024–26 | Parcel volume into African hubs; demand for local 3PL, returns and last-mile partners |
- Africa → EU exports shift from competing on price to competing on data. Exporters that can prove origin and deforestation-free sourcing keep EU access; Kenya and Uganda are among the early movers on coffee.
- EU → Africa e-commerce is losing to China on price and speed. European brands will likely need bulk shipping into African fulfilment centres rather than parcel-by-parcel delivery.
- Small parcels into the EU become more expensive, which also hurts African cross-border sellers and pushes them toward consolidated shipments and EU-based stock.
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| EUDR traceability and farm mapping | EU importers, exporters, co-ops | Low | Medium (rising) | Coffee and cocoa co-ops before the December 2026 deadline |
| EUDR-ready logistics (segregated storage, chain of custody) | Exporters | Medium | Low | Warehouses and transport for one export commodity |
| EU-registered operator services for African exporters | African exporters | Low | Low | Filing due-diligence statements on exporters’ behalf |
| Consolidated EU fulfilment for African brands | African brands (crafts, fashion, food, cosmetics) | Medium | Low | Bulk shipping to an EU warehouse to avoid per-parcel duties |
| Bulk-to-Africa fulfilment for European brands | EU brands | Medium | Medium | Stock in one African hub instead of parcel-by-parcel delivery |
| Global Gateway corridor contracts | EU- and DFI-funded projects | Varies | Medium | Corridor project pipelines (Abidjan–Lagos, Lobito, Northern Corridor) |
The EUDR deadline makes traceability the most time-sensitive opening in this guide. Dates for the EUDR and the EU customs reform are confirmed in law, but implementation details (the handling-fee amount, the data hub) may still shift.
Air cargo
Africa carries only about 2.1% of global air cargo, but it was the fastest-growing region in early 2026 (Nairametrics, citing IATA). Demand grew 18–21% year on year in January and February, then slowed to 1–3% by July and August as capacity grew faster than freight (Nairametrics). The Africa–Asia lane is the main growth engine, driven by perishables and trade deals with China.
- One dominant hub. Ethiopian Airlines is Africa’s largest carrier by cargo and is adding freighters. Addis Ababa absorbs much of the rerouted time-sensitive cargo (Ecofin).
- Fragile smaller carriers. Fuel makes up 30–40% of African airlines’ operating costs vs 20–25% globally, and smaller carriers such as ASKY have been reported under severe financial pressure (same source).
- Perishables drive exports. Flowers and vegetables (Kenya, Ethiopia), fish (Lake Victoria, Mauritania) and fruit (South Africa, Ghana) depend on air freight to Europe, the Middle East and Asia.
- Belly capacity matters. Much cargo flies in passenger aircraft, so routes follow passenger networks rather than freight demand.
- Liberalisation is slow. The Single African Air Transport Market (38 signatory states) is meant to open intra-African routes, but implementation lags.
- Blocked funds. About $1.2 billion of airline funds remain blocked from repatriation, 93% of it in Africa and the Middle East (FreshPlaza, citing IATA). This deters foreign carriers.
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| Cargo sales agency and consolidation | Exporters, airlines | Low | Medium | Consolidate small exporters onto Ethiopian, Kenya Airways or Gulf carriers |
| Airport perishables cold chain | Exporters | Medium | Medium | Pre-cooling and cool rooms at a secondary airport |
| Digital air cargo booking for SMEs | SME exporters, forwarders | Low | Low | Rate quotes and booking on one export lane |
| Cross-border e-commerce air freight | Platforms, integrators | Medium | High | Consolidated parcel flows from China or the Gulf into one hub |
| Regional feeder freight | Shippers in secondary cities and landlocked markets | High | Low | Charter or drone links for medical and high-value cargo |
Monthly IATA figures swing sharply; use the annual trend.
Warehousing and industrial real estate
Modern Grade A warehousing is concentrated in Johannesburg, Cape Town, Durban, Nairobi, Lagos, Cairo and Casablanca (All Business Africa). The opportunity is split: large DFI-backed parks for multinationals, and a much less served middle market for SMEs and e-commerce sellers (see warehousing openings for early founders).
| Developer / operator | Where | Model | Backers |
|---|---|---|---|
| Africa Logistics Properties (ALP) | Nairobi (Tatu, Tilisi; further African capitals planned) | Grade A parks for lease, plus SME units | IFC, British International Investment (ex-CDC), Maris, Mbuyu |
| Infinity Industrial Park | Nairobi Eastern Bypass, about 200 acres | Industrial and logistics park | Private developers |
| Tatu City / Tatu Industrial Park | Nairobi north | Special economic zone with logistics land | Rendeavour |
| Nairobi Gate Industrial Park | Nairobi, near JKIA and the inland container depot | Build-to-suit Grade A warehousing (Turner & Townsend) | Improvon and Actis joint venture |
| TY Logistics Park | Lekki Free Zone, Lagos (near Lekki deep-sea port) | Grade A warehousing with 3PL, cross-docking, last mile | Private |
| AGL (MSC group) | Port hinterlands, e.g. Abidjan, Lagos, Gabon (Kobe-Kobe, April 2026) | Port-linked logistics zones and inland depots | MSC |
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| Secondary-city warehousing | FMCG, distributors, 3PLs | High | Low | Pre-leased build with an anchor tenant (Kisumu, Mwanza, Kano, Kumasi) |
| Inland bonded warehousing | Importers | Medium–high | Low | Near borders and inland depots |
Cold pallet storage is following the same pattern: Africa Go Green Fund put $18 million into an 8,000-pallet facility in Kampala for FMCG, pharma and retail.
Rents, vacancy and land prices are dated and differ by source, so they are left out here. Pull fresh broker data (Knight Frank, JLL, Broll) before any investment decision.
Fleet electrification, in brief
Electric two-wheelers are past the pilot stage in East Africa and are moving into Nigeria and Francophone West Africa. Electric motorcycle sales in Africa grew from under 1,000 in 2020 to about 70,000 in 2025, according to the IEA (Ecofin). Electric buses are following in Kenya and Rwanda; electric trucks remain early. Spiro reported more than 135,000 bikes, 2,500+ swap stations and 50 million+ swaps by September 2026 (EV Reporter).
Policy is supportive but unstable. In May 2026, Kenya’s Finance Bill proposed removing the zero VAT rating on electric vehicles, and Parliament rejected the change in June, keeping the zero rating in the Finance Act 2026 (The Standard; Nation). The operators, policy by country and rider economics are in our guide to electric mobility startups in Africa.
Who funds logistics in Africa
Logistics and transport overtook fintech as Africa’s most-funded startup sector in January–September 2026: $780 million (36%) against $760 million (35%) (Tekedia, citing Africa: The Big Deal). Two companies made up about 76% of that: Spiro ($345 million) and Moove ($250 million) (Nairametrics). In the first half alone the sector raised about $472 million, 35% of all funding, up from a previous peak share of 13% in 2024 (Africa: The Big Deal, via Infor Capital). Spiro’s four H1 rounds ($7 million, $50 million, $215 million and $55 million, mixing debt and equity) came to about $327 million, around 70% of the H1 sector total (Nairametrics; TechCabal). Excluding Spiro, logistics funding is flat at roughly $110–150 million per half-year. Capital is concentrating in fewer, larger, debt-heavy deals.
- Totals. African startups raised $1.36–1.44 billion in H1 2026, roughly flat year on year, but disclosed deals fell from 252 to 146 (bne IntelliNews, citing TechCabal Insights). For the wider picture, see startup funding in East Africa.
- Logistics by half-year. About $221 million in H1 2024, $114 million in H1 2025 and about $465 million in H1 2026 (TechCabal Insights; bne IntelliNews). The sector raised about $1.8 billion over five years to mid-2025.
- Debt is rising. Debt raised by African startups grew from $1.01 billion in 2024 to $1.64 billion in 2025, per Partech (Capmad). Asset-heavy logistics (vehicles, batteries, warehouses) is a natural fit for debt; see freight finance.
- Consolidation. M&A accelerated sharply in H1 2026. Shutdowns since 2023 include Sendy, WhereIsMyTransport, MAX, Heroshe and Hytch (TechCabal Insights).
- Geography is widening. The “Big Four” (Nigeria, Egypt, Kenya, South Africa) took 58% of H1 2026 funding, down from 78% in H1 2025; Egypt alone took 27% (NTU Centre for African Studies).
Notable logistics and mobility rounds, 2025–26 (as reported):
| Company | Country | Segment | Round |
|---|---|---|---|
| Spiro | Pan-African (Kenya HQ) | E-motorcycles, battery swapping | About $327M in H1 2026 and $345M in January–September (equity and debt) |
| Moove | Pan-African (Nigeria-founded) | Vehicle finance for ride-hailing and delivery drivers | $250M (2026) (Nairametrics) |
| GoCab | Francophone Africa | Mobility, driver vehicle finance | $15M seed plus $30M debt (February 2026) (Nairametrics) |
| Bosta | Egypt | E-commerce delivery | $32M (February 2026) (AU-Startups) |
| Gozem | Togo, pan-West Africa | Mobility, delivery, vehicle finance | $30M Series B (2025); about $25M more in H1 2026 |
| Lula | South Africa | Mobility | About $21M (H1 2026) |
| Dodai | Ethiopia | E-motorcycles | $13M (April 2026) |
| Leta | Kenya | Logistics routing SaaS | $5M seed (March 2025) |
| Shiprazor | South Africa | E-commerce logistics | $2.65M seed (April 2026) |
| Investor type | Examples | What they fund |
|---|---|---|
| DFIs and development banks | IFC, British International Investment, US DFC, Proparco, FMO, Impact Fund Denmark, Afreximbank/FEDA | Debt facilities, warehousing and fleet assets, later-stage equity |
| Climate and blended-finance funds | Africa Go Green Fund (Cygnum), Nithio, InfraCo Africa, ALMA | E-mobility, cold chain, asset-backed debt |
| Africa-focused VCs | Partech Africa, TLcom, Novastar, Verod-Kepple, Ingressive Capital, Algebra Ventures (Egypt) | Seed to Series B |
| Global VCs | Speedinvest, Left Lane Capital, Y Combinator | Mobility fintech, marketplaces |
| Corporates and strategics | Maersk, Toyota Tsusho, MOL PLUS (Mitsui O.S.K.), Uber, Chinese e-mobility suppliers | Strategic stakes, supply partnerships |
Trackers (Africa: The Big Deal, TechCabal Insights, Partech, AU-Startups) count differently, so totals for the same period can differ by 5–10%. Spiro’s size distorts every sector figure for 2026.
Before you expand: a checklist for logistics scaleups
Investors in African logistics have seen many companies grow into new countries before the first one worked. Before you raise for expansion, be able to show:
- One profitable lane, city or corridor. Contribution margin per load or per drop, after payment costs, with at least one anchor customer who renews.
- A working-capital plan. How long you wait to be paid, how fast you pay drivers and partners, and which debt line funds the gap.
- A reason the next market is ready now. A corridor change, a new concession, a regulation deadline or an anchor customer who already ships there.
- A local route in. Licences, a partner (port operator, shipping line, distributor) and a country lead who knows the customs and labour rules.
- A data room a lender can use. Repayment, utilisation and delivery data by month, the basis for asset-backed debt.
Where Revise fits
Revise Scale is our track for companies with paying customers, revenue or a funding round. It is coming soon. Companies in the programme can become eligible for up to 100k USD in co-investment from Revise Angels, alongside their lead investor and subject to our investment committee. Request information now and you will hear first.
Earlier stage? Revise Launch takes idea-stage founders to their first paying customers.
Scaling a logistics company?
Applying to Launch is free and takes about five minutes. A person reads every application.
Frequently asked questions
How big is the African logistics market?
Outsourced logistics is roughly $150–250 billion a year; Ken Research puts third-party logistics and warehousing at about $185 billion. Total logistics cost, including in-house transport and storage, is about $370–510 billion by our estimate. Published figures differ by 2–9×.
Which African trade corridors matter most for logistics startups?
The Northern Corridor (Mombasa–Kampala), the Central Corridor (Dar es Salaam), the Lobito Corridor, Abidjan–Lagos, and the Maputo, North–South and Djibouti corridors. Openings cluster where something is changing, such as new rail, a port concession or a new border system.
Has AfCFTA made cross-border trade in Africa duty-free?
Not yet in practice. Most tariff schedules are verified, but duty savings apply only where both countries have gazetted and applied the cuts. Non-tariff barriers still matter more than tariffs for most cargo.
What does the EU deforestation regulation mean for African exporters?
From 30 December 2026, large and medium operators must prove that coffee, cocoa, palm oil, rubber, timber, soy and cattle come from geolocated, deforestation-free sources. Small operators follow from 30 June 2027.
How much funding do African logistics startups raise?
Logistics and transport raised $780 million in January–September 2026, 36% of all African startup funding. Two companies, Spiro and Moove, took about 76% of it, and debt plays a growing role.
Who invests in African logistics companies?
DFIs such as IFC and British International Investment, climate and blended-finance funds such as Africa Go Green Fund, Africa-focused VCs such as Partech Africa and TLcom, and strategics such as Maersk and Toyota Tsusho.
Keep reading
Sources
All links accessed in October 2026. Volumes, concessions, policy and funding change quickly; check them before you act.
- Market size:
- Corridors: Engineering News, Mining Weekly
- Ports:
- AfCFTA:
- EU–Africa:
- Air cargo: Nairametrics, July, Nairametrics, August, Ecofin, FreshPlaza
- Warehousing: All Business Africa, Intelligent CIO, Business Chief, Turner & Townsend, Capmad
- E-mobility: Ecofin, citing IEA, EV Reporter, The Standard, Nation
- Funding:
Rebecka Hald writes about startups, accelerators and early-stage funding in Africa for Revise. Her guides look at what programmes and investors actually offer founders, and what it takes to get from idea to first paying customers.
Revise guides are fact-checked and every source is linked. We update them when programmes, terms or numbers change.