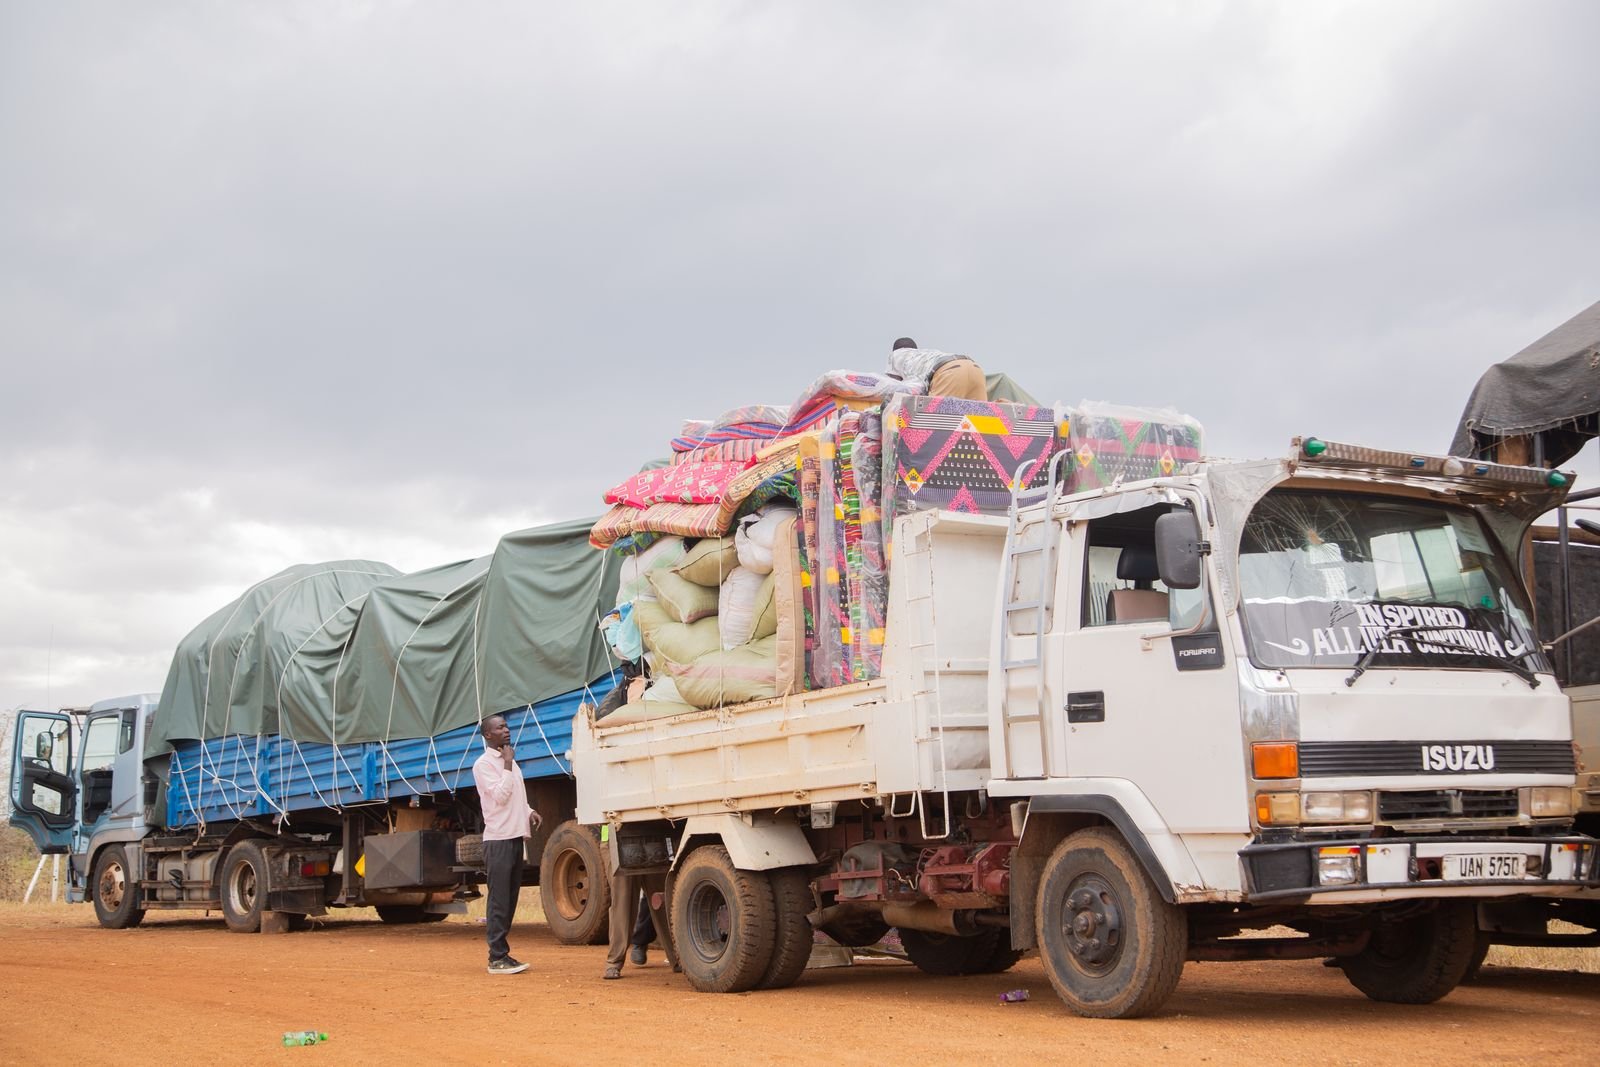
Truckers follow whoever pays them fastest. This guide explains the freight finance products that keep African logistics moving, why the startups that survived built them, and how to start one.
In this guide
Why is payment the real product in African logistics?
The short answer
Shippers pay in 30–90 days, while drivers need fuel cash upfront, and truck-financing penetration in Africa is below 1%. Whoever closes that gap earns the trucker’s loyalty. That is why the logistics startups that survived the 2018–2022 wave make money on finance and reliability, not on matching loads.
- Logistics data (trips, invoices, fuel use) is the best credit signal available for small transporters, where bank credit files do not exist.
- Freight factoring, fuel credit, revenue-based vehicle finance, goods-in-transit insurance and cross-border payments can each sit on top of several logistics platforms.
- Fund the float with debt from DFIs and impact funds, not venture equity.
- Credit, insurance and lending licences shape the structure, and they differ by country.
The working-capital gap
Most trucks in Africa are owned by people with 1–5 vehicles. They reach shippers through 2–4 informal brokers, each taking a cut, partly because payment and credit run through those brokers. Shippers pay in 30–90 days; drivers need fuel cash before the trip. Thin SME balance sheets and weak credit data keep banks out.
Truck-financing penetration in Africa is below 1% (Nairametrics, on Moove × Lori; BusinessDay, on Autochek). New heavy trucks worth about $2.7 billion were sold in Africa in 2025 (Mordor), so most of that is paid in cash or on informal credit.
What the first logistics startup wave taught us about money
The digital freight marketplaces of 2018–2022 raised hundreds of millions of dollars, and most of them shrank or shut down (more on the failures). Two of their lessons are about money:
- Matching is not the product, payment is. Truckers join for fast payment. Shippers stay for reliability. The marketplace is the delivery mechanism for working capital.
- Debt beats equity for float. Survivors fund payments with debt facilities from DFIs and banks, not with venture equity.
The clearest example is Trella. The Egyptian B2B trucking marketplace raised a $42 million Series A, led in part by Maersk, and added debt lines from ALMA and the US DFC to fund faster trucker payments (Techloy). Kobo360 shows the other side. It paid truck drivers upfront while waiting 30 to 90 days to be paid by manufacturers and distributors. When a bank partner pulled its credit line, the cash flow collapsed and it cut operations. In 2025 its investors sold their shares to co-founder Obi Ozor, who took on ₦10 billion ($15.8 million) of debt (Dabafinance). Lori Systems has since moved to a model where banks fund drivers upfront and collect from cargo owners (Dabafinance). The bank is the float.
Freight finance products, and who uses them
| Product | Who pays | Credit signal used | Example operators (verify current status) | Main risk |
|---|---|---|---|---|
| Freight invoice factoring | Shipper’s invoice discounted for the transporter | Shipper’s payment record | Trella (with ALMA/DFC debt), banks with logistics desks | Shipper pays late or disputes delivery |
| Fuel credit and fuel cards | Transporter, repaid from trip payouts | Trip history on the platform | Marketplace-linked programmes; fuel retailers | Diversion of fuel, fraud |
| Revenue-based vehicle finance | Driver or owner-operator, repaid as a share of weekly earnings | Earnings on platform | Moove (Uber’s vehicle partner in sub-Saharan Africa; partnered with Lori for trucks) | Vehicle recovery, earnings volatility |
| Truck loan marketplaces | Buyer, via partner lenders | Dealer and lender scoring | Autochek (Nigeria, Ghana) | Thin lender appetite for used trucks |
| Asset-backed e-bike and EV finance | Rider, daily or weekly instalments | Telematics and battery-swap data | E-mobility operators (see our electric mobility guide) | Battery and residual-value risk |
| Cargo and goods-in-transit insurance | Shipper or transporter, per trip | Route, cargo and GPS data | Embedded insurance players and insurers | Claims fraud, low trust |
| Cross-border payment and FX | Shipper or forwarder | Transaction history | PAPSS-linked rails, mobile money, payment fintechs | FX controls, liquidity in some currencies |
Why freight finance works now
- The data exists. GPS, electronic proof of delivery (e-POD), mobile-money payouts and platform trip logs make underwriting possible where bank credit files do not exist.
- Debt is available. DFIs (DFC, IFC, British International Investment, Proparco, FMO) and impact debt funds such as ALMA provide warehouse lines to platforms that show repayment data.
- Logistics firms need it to survive. Fast payment is what keeps truckers on a platform.
- Payments are getting easier across borders. Links such as Kenya’s Pesalink with the Pan-African Payment and Settlement System (PAPSS) make intra-African logistics fees easier to settle.
Where founders can start
Finance products can sit on top of several logistics platforms rather than inside one. Lender-of-record rules differ by country and shape the structure. In the table, “capital need” and “competition” are our assessment, not measured data.
| Opening | Who pays | Capital need | Competition | Entry point |
|---|---|---|---|---|
| Freight invoice factoring | Transporters (discount), shippers | Medium (debt-funded) | Low | Verified invoices from a logistics platform partner, or one large shipper’s payables |
| Trucker payment and working-capital layer | Transporters | Medium (debt-funded) | Low | Serve existing brokers rather than replace them |
| Fuel credit and fuel cards | Transporters | Medium (debt-funded) | Low | Partnership with a fuel retailer |
| Revenue-based vehicle and e-bike finance | Drivers, riders | High (debt-funded) | Medium | Telematics-linked portfolio with a fleet or swap operator |
| Goods-in-transit insurance | Shippers, transporters | Low (insurer carries the risk) | Low | Embedded per-trip cover on a booking platform |
| Cross-border freight payments and FX | Forwarders, shippers | Low–medium | Medium | PAPSS-linked payments on one corridor |
Who should build this
Freight finance suits founders who understand credit: people from banking, microfinance, insurance or a fintech’s risk team. You will still need a co-founder who knows trucking or couriers, because the hard part is verifying that a delivery really happened. If you are missing that person, see our guide to finding a co-founder.
How to start without a balance sheet
- Find the data partner first. A logistics platform, a fuel retailer or a large shipper whose invoices and trip data you can see. Without verified data you cannot underwrite.
- Start with the strongest payer. Factor the invoices of one shipper with a reliable payment record. That shipper’s risk, not the trucker’s, is what you price.
- Use a licensed partner. A bank or licensed lender can act as lender of record while you build the product, the data and the collections process.
- Keep the first book small and clean. Track repayment, disputes, days to cash and losses by month. That record is what a DFI or debt fund asks for before it gives you a warehouse line.
- Plan for fraud from day one. Fuel diversion, fake deliveries and claims fraud are the main risks in the table above. Bake checks (GPS, e-POD, fuel-station data) into the product.
How freight finance is funded
| Route | Typical providers | Best fit | What unlocks it |
|---|---|---|---|
| Asset-backed debt and warehouse lines | DFIs (IFC, British International Investment, US DFC, Proparco, FMO), impact and climate funds (ALMA, Africa Go Green Fund, Nithio) | Receivables, fleets, e-bikes | A clean repayment and utilisation data room |
| Venture equity | Africa-focused and global VCs | The software and data layer, the team | Proven unit economics on one market or lane |
| Strategic investment | Shipping lines, OEMs, platforms | Companies that bring them demand or distribution | Commercial contract first, equity second |
Debt raised by African startups grew from $1.01 billion in 2024 to $1.64 billion in 2025, per Partech (Capmad). In February 2026, GoCab, which finances vehicles for drivers in Francophone Africa, raised a $15 million seed round plus $30 million in debt (Nairametrics).
Equity is the expensive way to fund a loan book. Our calculator shows what equity really costs when the company grows. For the wider funding picture, see who funds logistics in Africa and how to raise startup funding in East Africa.
How sure are these numbers? The product mechanics are reliable. Penetration figures are dated estimates, and operator lists and fundraising totals change quickly.
Where Revise fits
Building freight finance from scratch? Revise Launch helps idea-stage founders with team, customer discovery, the MVP and first paying customers. Already running a loan book or a platform with traction? Revise Scale is coming soon, with eligibility for up to 100k USD in co-investment from Revise Angels, subject to our investment committee.
Building freight finance?
Applying to Launch is free and takes about five minutes. A person reads every application.
Frequently asked questions
What is freight factoring?
Freight factoring pays a transporter now for a shipper’s invoice that is due in 30–90 days, in exchange for a discount. The factor then collects from the shipper, so the price depends mainly on the shipper’s payment record.
Why do logistics marketplaces in Africa need embedded finance?
Truckers join platforms that pay them fast and leave those that do not. The marketplaces that survived, such as Trella, fund fast trucker payments with debt. Kobo360 cut operations when a bank withdrew its credit line.
How common is truck financing in Africa?
Rare: truck-financing penetration in Africa is below 1%. Most of the roughly $2.7 billion of new heavy trucks sold in 2025 were bought with cash or informal credit.
Who lends to freight finance startups in Africa?
DFIs such as IFC, British International Investment, US DFC, Proparco and FMO, and impact debt funds such as ALMA, provide warehouse lines to platforms that can show repayment data.
Do I need a licence to offer freight finance?
Usually. Lending, factoring and insurance rules differ by country. Many startups begin with a bank or licensed lender as lender of record and a licensed insurer carrying the risk.
What are the main risks in freight finance?
Shippers who pay late or dispute deliveries, fuel diversion, fake deliveries, claims fraud, vehicle recovery and FX controls. Verified GPS, e-POD and payment data reduce most of them.
Keep reading
Sources
All links accessed in October 2026. Operator status and fundraising totals change quickly; check them before you act.
- Truck finance: Nairametrics, BusinessDay, Mordor
- Marketplaces: Techloy (Trella), Dabafinance (Kobo360), Dabafinance (Lori)
- Moove: Africa Global Funds
- Funding: Capmad, citing Partech, Nairametrics
Rebecka Hald writes about startups, accelerators and early-stage funding in Africa for Revise. Her guides look at what programmes and investors actually offer founders, and what it takes to get from idea to first paying customers.
Revise guides are fact-checked and every source is linked. We update them when programmes, terms or numbers change.